tool · Risk & sizing
Risk and Reward Ratio Calculator with Costs
Compare modeled target and stop outcomes after costs, solve a cost-adjusted exit, or derive hypothetical price levels from an entry, a user-entered tick size and whole-tick distances.
Key points
- Reward-to-risk describes modeled amounts, not the probability of a fill or profit.
- A signed cost-adjusted zero-net exit can lie above or below entry depending on direction and financing credits.
- Tick-distance mode derives hypothetical levels from a declared fixed tick grid; it does not submit an order or verify platform rules.
- Calculated prices must be checked against the exact instrument specification, broker rules and actual fills.
Risk and reward ratio calculator
The starting numbers are illustrative inputs. Replace them with a consistent scenario. Calculations run in your browser; no account connection or live market data is used.
Formula and boundaries
Evaluate and find target: modeled risk A = |entry − stop| × quantity + fixed cost; find target = entry ± (requested ratio × A + cost) / quantity. Zero-net exit: entry ± (spread cost + commission + signed financing) / quantity. Tick-distance levels: stop = entry − direction × stop ticks × tick size; target = entry + direction × target ticks × tick size, where direction is +1 for long and −1 for short.
- Entry, stop and target use the same linear quoted-price unit. Quantity is in those units, not an unspecified futures contract count.
- Evaluate and Find target use one nonnegative fixed total round-trip cost. Zero-net exit instead separates spread, commission and signed financing; all monetary inputs use the same quote currency.
- If executable entry and exit prices already include the bid–ask spread, enter zero additional spread cost. Never count an expense twice.
- Tick-distance mode requires an entry on a constant, zero-origin grid. It uses a whole number of ticks and a tick size supplied by you; it does not infer instrument specifications or calculate monetary risk.
- Tick-distance levels are hypothetical prices only. This mode does not verify platform stop-distance rules, submit orders or create linked/OCO bracket legs.
- This positive-price model returns an unrounded mathematical price. Check the instrument tick grid and re-evaluate any permitted rounded price.
- A target price, stop price or zero-net exit is a scenario; none is a guaranteed fill or a recommendation.
Scope and assumptions
- Linear price change multiplied by positive underlying quantity produces quote-currency profit or loss.
- The Evaluate target and Find target modes use one nonnegative fixed total cost; Find zero-net exit separates spread and commission from signed financing. All monetary inputs use one quote currency.
- The zero-net exit mode assumes a positive underlying quantity and linear price profit. Contract multipliers, currency conversion and nonlinear payoffs require separate modeling.
- A desired net reward-to-risk ratio is a hypothetical input, not a success probability or recommendation.
- Evaluate and Find target return raw values without grid adjustment; tick-distance mode validates only a fixed zero-origin grid based on the user-entered tick size.
- Tick-distance mode returns hypothetical prices only; it does not calculate money, test platform stop-distance rules or verify order acceptance, linkage or fills.
- Stop and target execution, account-currency conversion, changing costs and copier behavior require separate verification.
Define the ratio without reversing it
Risk-to-reward and reward-to-risk are often written in opposite orders. This tool avoids that ambiguity by reporting the amount of modeled reward for each one unit of modeled risk. A result of 2 means the favorable amount is twice the adverse amount. It does not mean a two-to-one chance of winning.
For a long scenario, gross risk per unit is entry minus stop and gross reward per unit is target minus entry. A short scenario reverses those differences. Multiplying by quantity converts price differences into money for a linear unit-price instrument. The entered total round-trip cost is added to the adverse amount and subtracted from the favorable amount. cTrader documents the entry, stop and target relationship; this page's calculation is an independent educational model.
See the effect of costs
Assume a long entry at 100, stop at 96, target at 110, quantity of 20 underlying units and total modeled round-trip cost of 6. Gross downside is 4 × 20 = 80, becoming 86 after costs. Gross upside is 10 × 20 = 200, becoming 194 after costs. Reward per risk is 194 ÷ 86, approximately 2.25581.
Without costs the distance ratio is 10 ÷ 4 = 2.5. The lower cost-adjusted result is not an error: the same fee worsens both outcomes. In a matching short example, entry 100, stop 104 and target 90 produce the same arithmetic. Choosing short without changing the stop and target order is invalid.
Find the target for a desired net reward-to-risk ratio
The inverse mode answers a different question: given an entry, stop, quantity, costs and desired ratio, which hypothetical target makes the arithmetic balance? Select Find target and enter a positive desired net reward-to-risk ratio R. You choose R; the tool does not recommend it or estimate the chance of reaching the resulting price.
Let E be entry price, S the stop price, Q the positive quantity of underlying units, and C the nonnegative total round-trip cost for the entire position. This model uses the same fixed C in either outcome and keeps all money in the price's quote currency. First compute the adverse amount A = |E − S| × Q + C. The desired net favorable amount is R × A. Because exiting at the target also incurs C, the required gross favorable amount is R × A + C.
Long target = E + (R × A + C) ÷ Q. Short target = E − (R × A + C) ÷ Q. This is algebra for the stated linear model, not a platform order-setting rule. Simply multiplying the stop distance by R ignores the effect of costs on both outcomes. When C is zero, the formula reduces to that familiar distance calculation.
Verify the long and short targets
Use fictional prices quoted in USD per underlying unit, Q = 20 units, total round-trip cost C = $6 and desired ratio R = 2. These are illustrative assumptions, not market prices or fee quotes. Both examples below have a four-dollar adverse price distance, so A = 4 × 20 + 6 = $86. Desired net reward is 2 × 86 = $172. Gross favorable movement must therefore produce $178, requiring 178 ÷ 20 = $8.90 per unit.
| Scenario | Entry / stop | Raw target | Net reward / adverse amount |
|---|---|---|---|
| Long | 100 / 96 | 108.90 | ((108.90 − 100) × 20 − 6) / 86 = 2 |
| Short | 100 / 104 | 91.10 | ((100 − 91.10) × 20 − 6) / 86 = 2 |
Without costs, a long target of 108 would give a distance ratio of 2. With the stated $6 charge, however, that target produces net reward of $154 and an adverse amount of $86: approximately 1.79070 per unit of modeled risk. The inverse calculation moves the hypothetical target to 108.90 to recover the requested net ratio under the same assumptions. Moving a target does not make it more likely to fill.
Check a raw target against the instrument
The calculated target is an unrounded mathematical price. MetaQuotes lists tick size, contract size, calculation mode and minimum stop distance as separate instrument properties. Check the actual broker specification rather than inferring a valid order price from the number of decimals displayed.
For a purely hypothetical grid spaced by 0.25 with valid prices at 108.75 and 109.00, the long raw result 108.90 is off-grid. At 108.75 the same forward calculation gives (8.75 × 20 − 6) ÷ 86 = 169 ÷ 86, approximately 1.96512. At 109.00 it gives 174 ÷ 86, approximately 2.02326. Neither is exactly 2. Recalculate the ratio at any permitted price you choose; this tool does not round automatically or establish broker acceptance.
The interface requires positive prices, positive quantity and, in inverse mode, a positive desired ratio. A short scenario whose requested reward implies a target at or below zero is outside this tool's positive-price domain. That rejection is a model boundary, not a statement that negative prices are impossible in every market.
Use quantity and currency consistently
The quantity means underlying units whose price is expressed in the entered quote currency. An unspecified futures contract count is not interchangeable with those units. A contract multiplier must be incorporated first, and inverse instruments require a different model. Costs must be in the same currency as the resulting price difference times quantity. MetaQuotes describes OrderCalcProfit as an account-currency estimate under the current account and market conditions; this browser tool does not invoke that function or reproduce every instrument calculation mode.
C is a total for opening and closing the whole modeled position, not a per-unit fee and not a separate charge for each side. A $3 opening fee plus $3 closing fee would contribute $6 once to each scenario. If costs depend on exit price, holding time, quantity tiers or outcome, the same-C assumption no longer captures them. Model those outcomes separately rather than claiming the inverse target is exact for the account.
Do not include an expense twice if it is already represented by the entry or exit prices. Also distinguish a quoted target from an executable bid or ask. The calculator does not model spread dynamics, partial fills or the order book, and it does not fetch a market price.
Find the cost-adjusted zero-net exit
Find zero-net exit answers a different question from break-even win rate: at what price does a single position have zero modeled net result? Choose long or short, a positive entry E and positive underlying quantity Q. For this linear quote-currency model, let S be additional spread cost not already in executable entry and exit prices, K total round-trip commission, and F signed financing for the holding period (positive debit or negative credit). The total adjustment is C = S + K + F. Long net result = (exit − E) × Q − C; short net result = (E − exit) × Q − C. Therefore long zero-net exit = E + C ÷ Q and short zero-net exit = E − C ÷ Q.
cTrader documents broker-set commissions and swaps; its Trade Watch lists swaps to be earned or paid. Enter the amounts for the whole modeled position in the same quote currency. If entry and exit are executable ask and bid prices that already contain the spread, set additional spread cost to zero. The tool does not fetch broker charges or convert currencies.
Reconcile long, short and financing-credit prices
In an invented example, entry is 100, quantity is 20, additional spread cost is 2, total commission is 3 and financing debit is 1. C is 6. The long raw zero-net exit is 100.30 and the short is 99.70; in either case gross price result is 6 and modeled net is zero. If the financing input is an 8-unit credit, C becomes −3, moving the long zero-net exit to 99.85 and the short to 100.15. A credit can put the threshold on the adverse side of entry without making the position risk-free.
| Direction | Financing | C | Raw exit | Net check |
|---|---|---|---|---|
| Long | 1 debit | 6 | 100.30 | (100.30 − 100) × 20 − 6 = 0 |
| Short | 1 debit | 6 | 99.70 | (100 − 99.70) × 20 − 6 = 0 |
| Long | 8 credit | −3 | 99.85 | (99.85 − 100) × 20 − (−3) = 0 |
| Short | 8 credit | −3 | 100.15 | (100 − 100.15) × 20 − (−3) = 0 |
Download the worked arithmetic CSV. It is a manual fictional worksheet, not a TradeCopier account export, broker fee quote or order template.
Check the tick grid before using any price
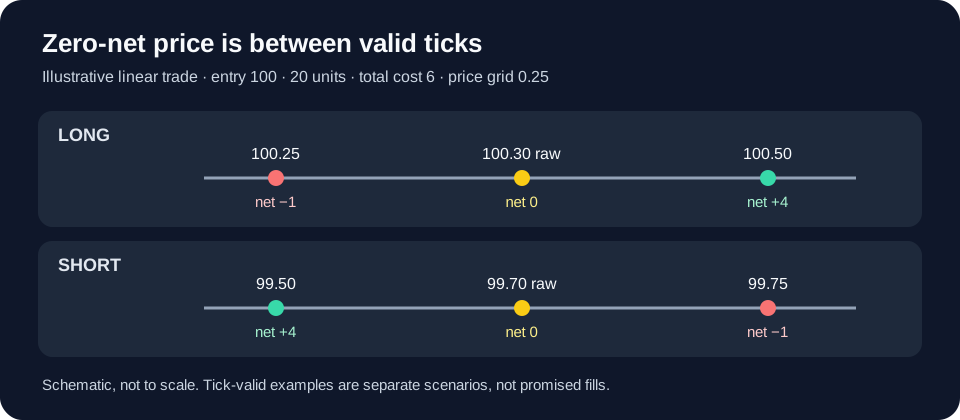
The raw mathematical exit may be off-grid. On a hypothetical 0.25 price grid, the long raw 100.30 lies between 100.25 (modeled net −1) and 100.50 (net +4). The short raw 99.70 lies between 99.50 (net +4) and 99.75 (net −1). Nearest-tick rounding can still leave a loss. Re-evaluate a broker-permitted price and actual charges rather than treating the raw threshold as a promised break-even stop.
MetaQuotes distinguishes tick size and contract calculation mode. Its OrderCalcProfit uses account and market conditions; this browser tool does not call it. A futures contract count needs its multiplier, while inverse or nonlinear instruments need another profit model. Broker order rules, changing costs, gaps and stop execution can make actual results differ from any calculated threshold.
Derive hypothetical bracket levels from tick distances
Enter an entry price, direction, the instrument tick size, and whole-tick stop and target distances to derive both hypothetical prices. For a long, stop = entry − stop ticks × tick size and target = entry + target ticks × tick size. For a short, the signs reverse. A tick is the instrument’s minimum price change; it is not automatically the same as a pip or point.
| Direction | Entry | Stop distance | Target distance | Hypothetical stop | Hypothetical target |
|---|---|---|---|---|---|
| Long | 4,321.25 | 12 ticks | 30 ticks | 4,318.25 | 4,328.75 |
| Short | 100.00 | 7 ticks | 18 ticks | 101.75 | 95.50 |
The entry must already lie on the fixed, zero-origin grid set by the entered tick size. The calculator rejects an off-grid entry rather than silently moving it, then derives the two prices from whole ticks. MetaQuotes lists the symbol’s minimum price change as a tick-size property and its stop-level property separately. Actual symbols can have different price increments, price-band rules and minimum distances relative to current quotes; this calculator does not check those settings, calculate money at risk, send an order or create linked/OCO bracket legs. Verify the exact platform and instrument rules before using a hypothetical price. MetaQuotes symbol-property reference.
Understand what the output cannot decide
The selected stop and target are scenarios, not guaranteed fills. A gap can exceed the intended stop, while a touched target may not fill every order. cTrader explains that a stop-loss exit uses the best available market price; the selected stop is therefore not a guaranteed cash-loss ceiling. If entered costs equal or exceed the gross target amount, the tool displays a zero or negative favorable amount with an explanatory note. Moving the target farther away can mechanically increase the ratio while reducing its chance of being reached.
Evaluate outcome probabilities separately using appropriately defined evidence. Keep the actual result in the trading journal even when it falls outside the planned range. For copied positions, compare the source and follower's own entries, fills and costs instead of assuming the same planned ratio produces the same realized return.
Questions and answers
Does a high reward-to-risk ratio mean a trade is profitable?
No. The ratio describes two assumed amounts. Profitability also depends on outcome probabilities, costs, execution and the completeness of the evidence.
How do I find a target from a desired net reward-to-risk ratio?
Calculate A = absolute entry-minus-stop distance × quantity + total cost. Required gross reward is desired ratio × A + total cost. Divide that by quantity, then add the distance to entry for a long or subtract it for a short. The fixed-cost linear assumptions must hold.
Why does a desired ratio of 2 produce a long target of 108.90 rather than 108?
For entry 100, stop 96, 20 underlying units and total cost 6, the adverse amount is 86. Net reward must be 172, so gross reward must be 178. That requires an 8.90 price movement. A target of 108 gives only 154 net reward, approximately 1.79070 times the adverse amount.
Is the cost entered per unit or for the entire trade?
Enter the nonnegative total round-trip cost for the whole position in the same quote currency as price movement times quantity. The model uses that same fixed total in both outcomes. Do not enter a per-unit cost or count expenses already embedded in the prices twice.
Can I enter lots or futures contracts as quantity?
Quantity represents underlying units compatible with the quoted price, not an unexplained lot or contract count. Establish the contract multiplier and calculation mode first. Inverse or nonlinear instruments need a different model.
How do I derive bracket prices from tick distances?
Enter the price, direction, tick size and whole-tick stop and target distances. For a long, stop = entry − stop ticks × tick size and target = entry + target ticks × tick size; reverse the signs for a short. For example, a long entry of 100 with a 0.25 tick, a 4-tick stop and an 8-tick target gives hypothetical prices of 99 and 102. This assumes a fixed zero-origin grid and does not calculate money or submit linked orders.
Can I send the calculated target or bracket levels directly to my broker?
No. The browser calculator does not submit orders or create linked/OCO bracket legs. Tick-distance mode checks its hypothetical prices only against the fixed, zero-origin increment you enter; it does not verify current quotes, price-band schedules, minimum stop distances, broker rules or fills.
Why does the tool reject my stop or target?
The active mode rejects missing or invalid inputs. Evaluate and Find target require the correct long or short price ordering; tick-distance mode requires positive whole-tick distances and tick size plus an entry on the declared grid. Derived nonpositive prices are outside the positive-price model.
Does the modeled adverse amount cap my actual loss?
No. Stop prices are scenarios, not guaranteed fills. Gaps, execution differences and changing costs can produce a larger loss. The calculator does not place orders, estimate outcome probabilities or verify TradeCopier stop handling.
How do I find a long or short zero-net exit price after costs?
For entry E and positive underlying quantity Q, sum additional spread cost, total round-trip commission and signed financing as C. The long zero-net exit is E + C ÷ Q; the short exit is E − C ÷ Q. This requires a linear same-currency price model.
Can a financing credit move the zero-net price past entry?
Yes. If a signed financing credit exceeds the other entered charges, C is negative. A long zero-net exit can then be below entry and a short exit above it. The credit and the exit fill are not guaranteed.
Should I add spread cost if my executable prices already contain the spread?
No. Set additional spread cost to zero when the entry and exit prices already include their bid–ask effect. Entering it again would double count the expense.
Is the calculated zero-net exit a guaranteed break-even stop?
No. It is an unrounded mathematical threshold. A broker price grid or order rule may reject it, and a triggered stop may fill elsewhere. Check the permitted level, actual fees and fill before drawing any conclusion.
Sources and further checks
Use the current source for your exact instrument, account and platform. Referencing a general specification does not establish support for every TradeCopier workflow.
- cTrader: risk and reward · Checked September 22, 2026
- MetaQuotes: estimating operation profit · Checked September 22, 2026
- MetaQuotes: tick size, minimum price change and stop-level properties · Checked September 24, 2026
- cTrader: orders and stop-loss execution · Checked September 22, 2026
- cTrader: trading conditions, commissions and swaps · Checked September 24, 2026
- cTrader: Trade Watch swaps earned or paid · Checked September 24, 2026
Found an error? Send a correction with this page's address and a primary source. See our editorial standards for how we handle examples, claims and revisions.