guide · Futures & contracts
Contango vs Backwardation: Read a Futures Curve and a Roll
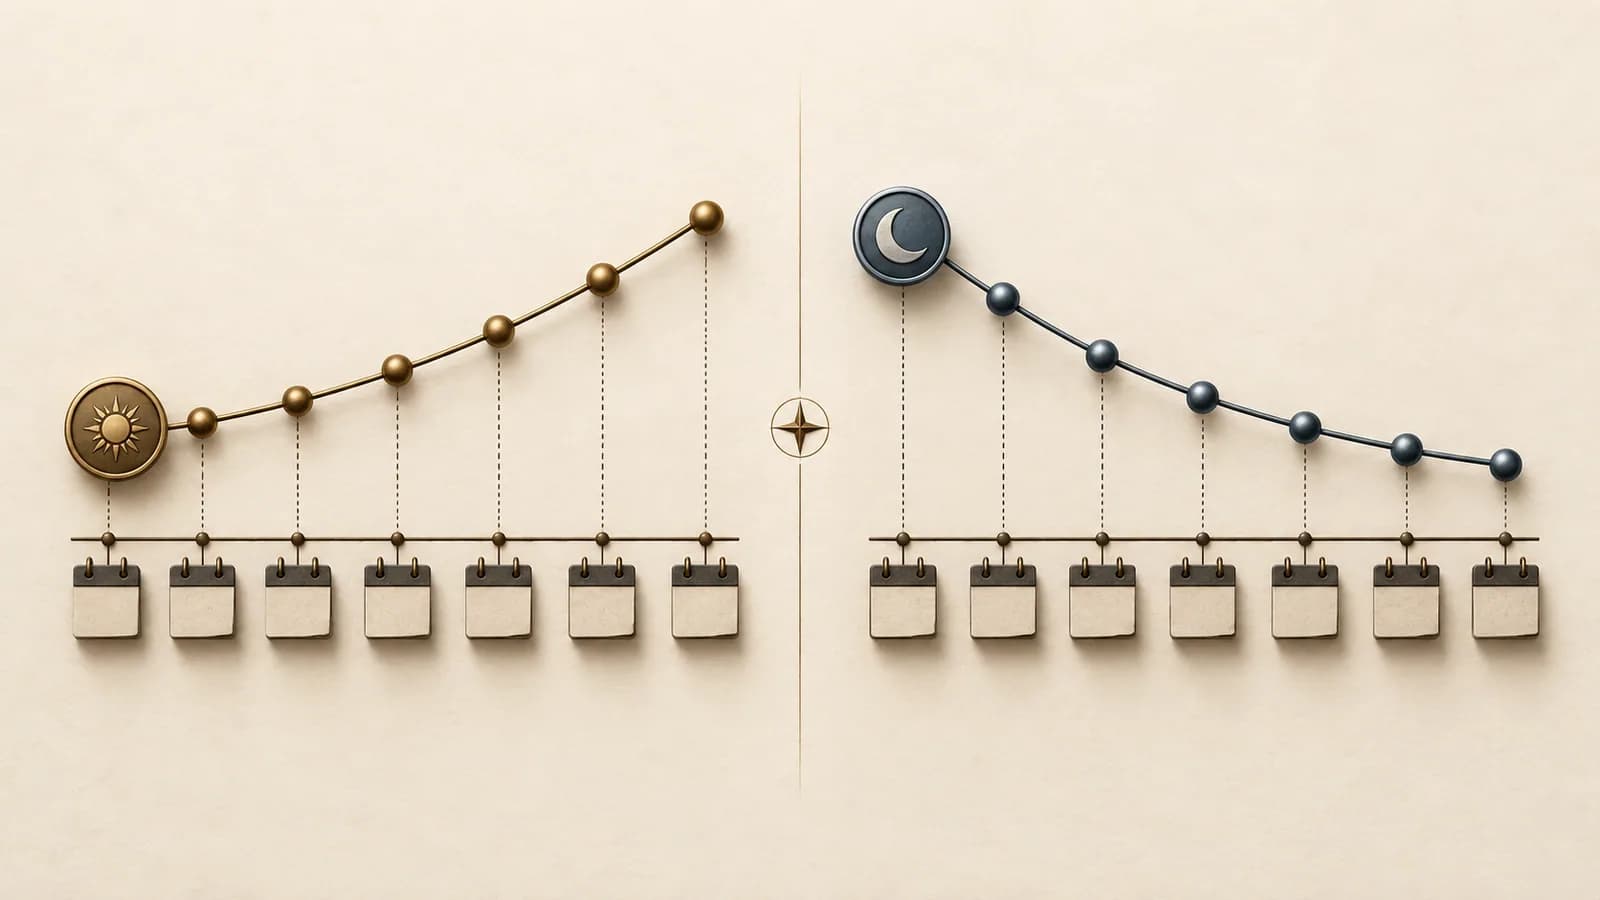
Contango describes futures priced above the relevant spot or nearer delivery reference; backwardation describes the opposite relationship. These terms describe prices across maturities at a given time. They do not by themselves predict whether the market price will rise or fall.
Key points
- Compare like-for-like prices observed at the same time and state the spread sign convention.
- The difference between contract months is not an immediate guaranteed gain or loss from rolling.
- Storage, financing, income and the value of available inventory can influence the curve.
- Continuous-chart returns can differ from a ledger of actual dated contracts and rolls.
Futures roll ledger and curve-gap calculator
The starting numbers are illustrative inputs. Replace them with a consistent scenario. Calculations run in your browser; no account connection or live market data is used.
Formula and boundaries
Each completed leg: signed (exit − entry) × multiplier × contracts. Combined net subtracts both entered round-trip costs. The indicative roll-gap ratio uses same-time near and deferred reference quotes: signed (near − deferred) ÷ near × 100.
- Use two dated contracts of the same linear product, multiplier, quote currency and whole-contract quantity. Enter actual fills separately from same-time reference quotes.
- The indicative roll-gap ratio is a curve comparison, not a cash charge, realized return, forecast, annualized yield or decomposition of every cause of a futures return.
- The net percentage uses old-entry notional as an explicitly chosen comparison denominator. It is not a return on posted margin or collateral.
- All prices and costs are supplied hypothetical inputs. Actual fills, daily variation, exchange/broker charges, taxes and broker account records can differ.
Scope and assumptions
- All price curves and transactions are hypothetical.
- Spread and basis signs are explicitly defined; other sources may use the reverse convention.
- No arbitrage, return, calendar-spread support or automatic-roll capability is promised.
Read across dates, not along a price chart
A futures curve places contract maturities on one axis and their prices at a common observation time on the other. A normal price chart instead follows one instrument or a constructed series through time. Confusing those two pictures leads to a common mistake: treating an upward curve as proof that prices will rise.
CME's introduction describes contango as a futures premium to spot and backwardation as a discount. Market commentary also commonly compares a nearer futures contract with a later one. State which reference you are using, because a market can have different shapes in different portions of its curve.
The numbers in this guide are hypothetical. They are a way to inspect the relationships, not a statement about today's oil, metals or equity market. A curve can shift and reshape after the observation; neither label is a buy or sell instruction.
Construct two small curves
| Reference | Example A | Example B |
|---|---|---|
| Comparable spot | $80 | $80 |
| Nearer contract | $81 | $79 |
| Later contract | $83 | $77 |
Example A is upward-sloping and priced above the chosen spot reference. Example B is downward-sloping and below that reference. If we define the calendar spread as later minus nearer, A has a +$2 spread and B has a −$2 spread. A screen using nearer minus later would show the opposite signs for the same economic relationship.
Write the convention into the worksheet rather than relying on a positive or negative number alone. Also record the grade, location, currency and unit behind the spot comparison. A price for a different physical delivery location is not automatically the right cash reference for an exchange contract.
Why holding something for later can have a price
For a storable commodity, financing inventory, storing it and insuring it can affect the relationship between immediate and later delivery. Having usable inventory now may also carry an operational benefit. A manufacturer that needs material today cannot always replace it with a promise of delivery several months away.
CME discusses those storage and inventory considerations in its curve lesson. They explain why a difference across maturities can have an economic basis; they do not give every participant a practical arbitrage. Access to storage, transport, funding, delivery eligibility and transaction costs matters.
Here is an original accounting illustration rather than a complete pricing model. Suppose obtaining and carrying one unit costs $80 now, plus $2 of assumed financing and $1 of storage over a selected period. With no other benefit or cost, those listed outlays total $83. If holding the available inventory has an estimated $2 operational benefit to a particular firm, its economic comparison changes. Neither $83 nor $81 is a guaranteed exchange price.
Different assets need different models. For an equity index, financing and expected dividends affect the relationship rather than warehouse rent. CME's equity-index fair-value explanation distinguishes theoretical value from actual traded prices. Do not apply a commodity storage story to every contract with a futures label.
Seasonality can make one label inadequate
Imagine consecutive maturities priced at $3.00, $3.20, $3.10 and $3.40 per unit. Some adjacent spreads slope upward and one slopes downward. Describing the whole sequence with only one label discards information. A useful analysis names the two dates or the section of the curve it concerns.
CME's energy calendar-spread discussion explains that seasonal demand can shape different parts of a curve. The practical task is to compare the actual maturities, not assume a perfectly smooth line. Event expectations and changing inventory conditions can affect one period more than another.
This matters when a continuous chart switches its selected contract. An apparent jump might reflect the price difference between two maturities, a data adjustment or an actual move. Before calling it a strategy gain or loss, identify which contract the account actually held.
Follow a roll through two actual positions
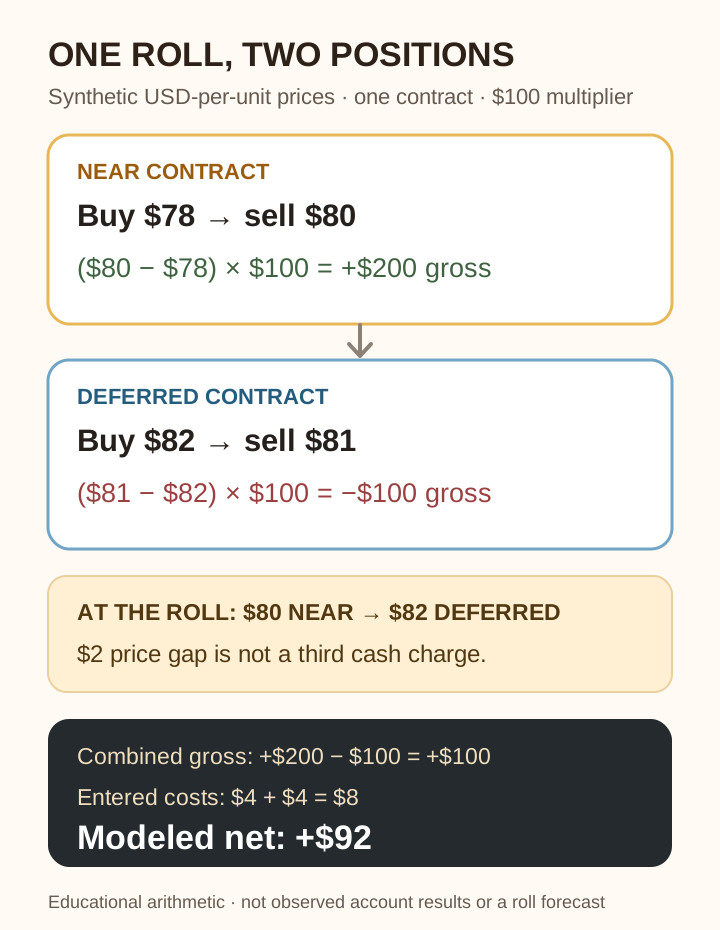
Consider an invented linear futures contract with a multiplier of 100 units. A trader buys the nearer contract at $78 per unit and later closes it at $80. The realized gross result on that contract is ($80 − $78) × 100 = $200.
At the roll time, the later contract is $82. The trader opens one later contract there and eventually closes it at $81. This second position loses ($81 − $82) × 100 = −$100. Combining both completed trades gives $100 before commissions and other costs.
The $2 difference between $80 and $82 at the roll was not an immediate $200 loss posted simply for exchanging the contract names. A futures opening normally establishes exposure with collateral and subsequent P&L; it is not a purchase of the full physical notional. The later contract's movement from its actual entry determines its trading result.
Nevertheless, the cross-month difference matters when comparing a rolled strategy with a spot series or a continuous front-month chart. A simplistic sequence from $78 to $80 to $81 would miss the new entry at $82. The proper ledger preserves both entries, both exits, quantities and fees. It is clearer than adding an assumed “roll fee” equal to the whole price gap.
Roll yield is a comparison with assumptions
Discussions of negative roll yield in contango and positive roll yield in backwardation describe an important tendency under particular holding and convergence assumptions. They should not be interpreted as a guaranteed cash payment on every roll. The shape can change, the underlying market can move and transaction costs can offset a modeled benefit.
To make a claim testable, specify the selected contracts, roll date rule, price observations, collateral treatment and return denominator. A fully funded notional return and a return on a small margin deposit are different measures. Comparing them without explanation can make an ordinary price movement look dramatically more or less attractive.
A hypothetical long later contract entered at $82 would lose $200 per 100-unit contract if its price later converged to an unchanged $80 reference. If the relevant market instead moved and that contract reached $85, it would gain $300. The initial curve label alone does not choose between those paths.
Basis and calendar spreads are related, not identical
Basis compares a futures price with a specified cash or spot reference. A calendar spread compares futures of different maturities. Use an explicit convention, such as futures minus spot for basis and later minus nearer for the calendar spread. Other markets or data providers may use the reverse sign.
For spot $80, near $81 and later $83, the stated basis values are +$1 and +$3. Their difference is the +$2 later-minus-nearer spread. If the spot reference comes from another time, this neat comparison loses meaning. A synchronized snapshot is part of the calculation, not just a reporting detail.
The contract-mechanics guide helps identify the underlying units. For operational expiration planning, use the existing rollover article. A price-curve interpretation does not replace the broker's actual last date for carrying a position.
Use the curve carefully in account comparisons
Two accounts holding the same product in different months can produce different prices and P&L without either execution being incorrect. Confirm the exact symbols before attributing the difference to slippage or a copier. The relative prices of those months can also change after entry, so a one-time offset is not a permanent correction.
If a workflow is meant to roll across several accounts, reconcile the old-contract exit and new-contract entry on each account separately. A source account completing both legs does not establish that every destination has done so. Check open positions and pending instructions, including their contract months.
The futures specification guide addresses those identity checks, while cash and physical settlement explains why the final deadline matters. The curve supplies context for prices; it does not prove that a particular software connection supports calendar spreads or automatic rolls.
Calculate a roll ledger without treating the gap as cash P&L
The calculator above keeps two completed contract legs and a same-time curve snapshot separate. For a long position, each leg's gross result is (exit fill − entry fill) × contract multiplier × whole-contract quantity; reverse the sign for a short. Subtract the entered round-trip cost for each leg to obtain the combined net. CME's contract P&L lesson explains price movement, tick value and quantity. A futures account can also settle variation during the holding period; the simple entry-to-exit ledger summarizes the price result rather than the timing of each cash adjustment, as described in CME's mark-to-market lesson.
The sample starts with the invented near contract bought at $78 and sold at $80, then a deferred contract bought at $82 and sold at $81. For one contract with a fictional $100 multiplier, the two gross results are +$200 and −$100. Entering $4 total round-trip cost on each leg leaves $92 combined net. The $2 difference between the near exit and deferred entry is an executed cross-month price gap; it is not a third $200 cash loss to subtract from those two legs.
For the indicative curve comparison, enter near and deferred reference quotes observed at the same time, in the same currency and price units. With near $80 and deferred $82, deferred minus near is +$2. For the calculator's stated long-position convention, the indicative signed gap ratio is (80 − 82) ÷ 80 = −2.5%. It is not a realized yield, forecast, fee, cash flow or annualized return. The modeled combined net divided by the old entry notional is $92 ÷ ($78 × 100) = approximately 1.1795%; that percentage uses a different denominator and includes both legs and costs. Neither is a return on margin.
| Record | Calculation | Boundary |
|---|---|---|
| Two completed legs | Signed fill changes × multiplier × contracts, less entered costs | Modeled trading result; check actual statement and daily variation |
| Same-time curve quotes | Deferred minus near; signed gap ÷ near | Indicative shape comparison, not a realized return |
| Old-entry notional | Old fill × multiplier × contracts | Declared percentage denominator, not posted collateral |
A hypothetical later convergence to an unchanged $80 reference would make the deferred contract entered at $82 lose $200 gross per 100-unit contract. An actual later exit at $81 instead loses $100 gross. The market can move, the curve can reshape, and the account can incur additional charges. Do not substitute the conditional convergence path for an observed fill.
Download a dated record and test the boundaries
Download three synthetic roll-ledger examples or start with the blank dated roll worksheet. The examples include a long contango scenario, a long backwardation scenario and a flat-price case with costs. They use fictional contracts and prices; no row represents TradeCopier, a broker account or today's market. The blank sheet leaves observed values empty and marks the outcome not_run.
Record the product and both full contract months, dated entry and exit fills, separate same-time reference-quote timestamps, currency, multiplier, quantity, commission and other included costs. If the two reference quotes were not comparable or simultaneous, leave the curve-gap interpretation unresolved. If either leg remains open, do not label its entry-to-current-price movement as realized P&L. A partial roll can leave different old and new quantities; the calculator intentionally requires the same whole-contract count and is not a partial-fill accounting tool.
The widget has no live quotes or broker connection. It does not determine expiration deadlines, margin eligibility, optimal roll timing, spread-order support, TradeCopier routing behavior or a trading decision. Reconcile the actual order, fill, daily variation and position records for every account before concluding a roll is complete.
Questions and answers
Does contango mean a futures price is expected to rise?
Not by itself. Contango describes a relationship across delivery dates or to spot at an observation time. Financing, storage and other factors can contribute to that relationship. It is not a reliable directional forecast for the contract you trade.
Do I immediately lose the price gap when I roll a long position in contango?
The two contract prices are not automatically an immediate cash loss equal to the notional gap. Record the old contract's actual entry and exit, then the new contract's entry and later result. The gap matters for rolled-return comparisons, with costs and assumptions stated.
Can a futures curve contain both contango and backwardation?
Yes. Different adjacent maturities can slope in different directions, particularly where seasonal or period-specific conditions matter. Name the contracts and sign convention instead of forcing a single label onto the entire curve.
Is the calculator's roll-gap ratio a realized roll yield?
No. It compares two same-time reference quotes using a stated sign and near-price denominator. It is not a cash charge, a realized return, an annualized rate or a forecast. The completed near and deferred contract fills are calculated separately.
Why does the ledger ask for both quotes and fills at the roll?
Same-time reference quotes describe the curve, while actual exit and entry fills describe the transactions. They can differ because of the timing, bid-ask spread and execution. The calculator does not infer one from the other.
Why is the net percentage divided by old-entry notional?
That is an explicit comparison basis: old entry price times multiplier times whole-contract quantity. It is not the cash deposited or a return on margin. A different denominator produces a different percentage, so compare only calculations using the same basis.
Does a positive calculated result prove an automatic roll will succeed?
No. The figures are hypothetical. Each actual account needs supported contract months, confirmed orders and fills, current broker rules and its own reconciliation. The calculator does not place or verify trades.
Sources and further checks
Use the current source for your exact instrument, account and platform. Referencing a general specification does not establish support for every TradeCopier workflow.
- CME: What Is Contango and Backwardation? · Checked September 19, 2026
- CME: Trading Energy Calendar Spread Options · Checked September 19, 2026
- CME: Futures Expiration and Contract Roll · Checked September 19, 2026
- CME: Calculating Futures Contract Profit or Loss · Checked September 19, 2026
- CME: Calculating Equity Index Fair Value · Checked September 19, 2026
- CME: Mark-to-Market · Checked September 23, 2026
Found an error? Send a correction with this page's address and a primary source. See our editorial standards for how we handle examples, claims and revisions.