guide · Technical analysis
Moving Average Crossover: Rules and Whipsaw Tests
A moving-average crossover occurs when the ordering of two specified average series changes. That event can define a research signal, but it is not a complete trading strategy until timing, orders, exits, size and costs are specified.
Define both averages before naming a crossover
A crossover compares two time series calculated from the same declared observations or from explicitly different ones. The shorter lookback is often called fast and the longer slow. The labels describe parameter choice; they do not guarantee a faster profitable response. State whether each series is simple, exponential, weighted or another construction.
A simple moving average adds the selected n observations and divides by n. As a new value arrives, the oldest leaves. Fidelity describes this equally weighted construction. The choice of close, open, midpoint or another input changes the underlying series, so “a 20-period average” is incomplete without its source.
An exponential average updates the previous estimate using a weight on the latest observation. A common coefficient is 2 / (n + 1). Fidelity explains the greater weight on recent observations. The starting value and amount of warm-up history can affect early results, unlike an exact simple average once its full rolling window is available.
Use a mathematical crossing condition
For an illustrative upward crossing, require fast to be greater than slow now, and fast to have been less than or equal to slow at the preceding completed observation. This distinguishes a new crossing from every bar on which the fast line remains above the slow. A downward crossing reverses the comparisons.
Equality needs a rule. If two averages are equal for several observations, should the first later separation qualify? The example above says yes after equality. Another specification might require a previously strict ordering. Neither should be silently selected by floating-point rounding or a chart's visual line thickness.
Declare any minimum separation in valid units and compare unrounded internal values if that is the intended calculation. Displaying two rounded values as 100.00 does not prove they are mathematically equal. Conversely, a tiny difference caused by numerical precision should not accidentally create thousands of spurious events.
Calculate a short original example
Use hypothetical completed closes of 100, 99, 98, 97, 98, 99 and 100. Compare a three-observation simple average with a five-observation simple average. These short lengths make the arithmetic visible; they are not proposed live parameters.
| Observation | Close | Fast SMA | Slow SMA | Relationship |
|---|---|---|---|---|
| 5 | 98 | 97.6667 | 98.4000 | Fast below |
| 6 | 99 | 98.0000 | 98.2000 | Fast below |
| 7 | 100 | 99.0000 | 98.4000 | Fast above |
The upward crossing is observed at the completion of observation seven under the stated rule. The fast mean uses 98, 99 and 100. The slow mean uses 98, 97, 98, 99 and 100. Keeping the actual windows visible makes it possible to audit a spreadsheet or code implementation.
The event is partly driven by which old observations leave each window. It is not an independent market transaction. Two strategies with the same chart signal can produce different outcomes because they submit different orders, size differently or wait for different confirmation timestamps.
Separate signal time from fill time
If the completed close of 100 is needed to calculate the crossing, a model cannot casually assume it knew that completed value early enough to enter at a favorable intrabar price. Specify the next available observation or an actual order mechanism with suitable timing. A backtest that gives itself the signal and an earlier fill uses information it did not yet have.
Suppose the next executable illustrative entry is 100.50. An exit later at 101.50 creates a one-unit gross price gain, not the 1.50-unit gain measured from the signal's close. At $10 per price unit, one contract earns $10 gross. If total entry and exit costs are $3, the net is $7 before any other stated charges.
This small example shows why a signal chart and an execution ledger answer different questions. It also shows why copying a source account's resulting trade can create another price difference on a follower. A visual crossing does not establish that every account could fill at the plotted line.
Compare SMA and EMA with a controlled test
For an EMA example, assume a previous value of 100, a new close of 104 and a coefficient of 0.25. The update is 100 + 0.25 × (104 − 100) = 101. Repeating this process carries an exponentially declining influence from earlier observations. It is not equivalent to dropping the oldest member of a finite equally weighted window.
To compare an SMA pair with an EMA pair, hold the input data, eligible sessions, orders, costs and exit rules constant. A comparison that also changes stop placement or timeframe cannot isolate the effect of weighting. Keep both full specifications in the report rather than presenting one line color as an inherently better approach.
Warm-up periods deserve explicit exclusion rules. Different history lengths can change an EMA's early crossings. If the first trades in a sample are important to the reported result, repeat the calculation with adequate preceding data and document whether the difference materially affects the conclusion.
Measure whipsaw instead of merely describing it
Whipsaw refers here to repeated ordering changes that fail to develop into sustained profitable movement under the selected trading rules. A range-bound sequence can create several crossings close together. A chart may make them look harmless because it does not deduct the spread and commission from each round trip.
Count crossing frequency, time between opposing events, turnover and the distribution of net results. Include the largest adverse outcomes as well as average trade profit. A lower number of signals may reduce costs but can also miss part of a move; a slower parameter is not automatically better simply because its chart appears smoother.
If adding an ADX condition or another filter, keep the unfiltered baseline. Record how many trades the filter removes, including winners. Adding a filter after inspecting losses creates another selection step and needs new evaluation rather than being presented as a free improvement.
Control live-bar and higher-timeframe behavior
An unfinished close can change repeatedly, moving the two averages across and back before the bar finishes. TradingView explains why historical and real-time calculations can differ. A bar-close rule and an intrabar rule are separate strategies, even if their final historical plot looks similar.
A lower-timeframe strategy using a higher-timeframe average needs a policy for unfinished higher-timeframe data. Do not use the final hourly value at the start of the hour unless it was already available. Record when each input became known, not just the chart coordinate at which it is eventually drawn.
Join hourly and 15-minute bars by availability time
The following prices and UTC timestamps are fictional. This original test fixture compares a simple average of two completed 15-minute closes with a simple average of two confirmed hourly closes. It is not a TradeCopier strategy, market observation, latency measurement or return claim. Download the hourly inputs and 15-minute decisions to reproduce it. In this exercise, each hourly close becomes available two seconds after its bar ends and each lower-timeframe decision occurs five seconds after its bar ends. Those offsets are illustrative, not measured service performance; a real test needs recorded receipt times.
The hourly bars ending at 09:00 and 10:00 close at 110 and 100, so the available hourly SMA(2) for the 10:15 through 10:45 decisions is (110 + 100) / 2 = 105. The 10:00–11:00 bar eventually closes at 96, but its final value is not available until 11:00:02. Keying it to its 10:00 start would backfill (100 + 96) / 2 = 98 into the 10:30 decision. QuantConnect distinguishes a bar's start from its end and explains when the close can be known; TradingView documents higher-timeframe historical lookahead and the different behavior of unfinished realtime bars.
| UTC decision | 15-minute close | Fast SMA | Available hourly SMA | Backfilled hourly SMA | Upward crossing? |
|---|---|---|---|---|---|
| 10:00:05 | 100 | — | 105 | 98 | None: fast average not warmed up |
| 10:15:05 | 94 | 97 | 105 | 98 | Not yet evaluable: no previous fast SMA |
| 10:30:05 | 103 | 98.5 | 105 | 98 | Safe: no; backfilled: false early cross |
| 10:45:05 | 97 | 100 | 105 | 98 | No new upward cross |
| 11:00:05 | 96 | 96.5 | 98 | 98 | No; new hourly close already available |
| 11:15:05 | 101 | 98.5 | 98 | 98 | Safe: yes, after hourly confirmation |
At each decision with two consecutive computed fast averages, this fixture calls an upward crossover only when the previous fast-minus-hourly spread is at most zero and the current spread is greater than zero. The first two CSV event flags are blank because the fast average has not warmed up enough to compare two values. At 10:15:05 and 10:30:05, the safe spreads are −8 and −6.5: no 10:30 cross. The backfilled spreads are −1 and +0.5: a false 10:30 cross. At 11:00:05 and 11:15:05, the safe spreads are −1.5 and +0.5, so the first valid upward cross is at 11:15. A positive current spread alone is a state, not proof of a new event.
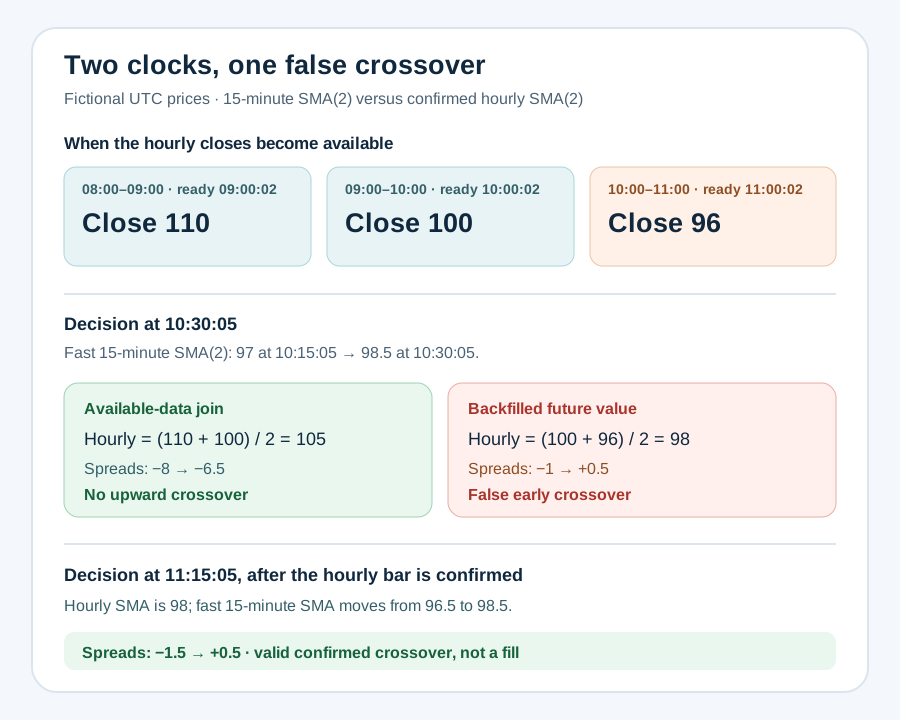
The 11:00 hourly close becomes available at 11:00:02 in the fixture, before the 11:00:05 lower-bar decision; that ordering is an explicit assumption. In production research, record actual confirmation and receipt time and define how equal timestamps are resolved. For a tabular backtest, sort on availability time and use a backward as-of join; pandas documents the sorted-key requirement and backward-join semantics. Joining on an hour's start label or silently using a forward join can reveal a final close before the strategy could see it. The broader look-ahead-bias guide covers the principle for other data. For a TradingView implementation, a historical no-lookahead setting alone does not settle realtime unfinished-bar behavior; its documentation gives an offset prior-bar expression with lookahead enabled for a confirmed, non-repainting higher-timeframe request.
A correct signal timeline is still not a fill ledger. TradingView's default strategy simulation explains that orders generated at a bar close normally fill on the next available tick. Your exact engine, order type, account and broker can differ. Preserve the signal timestamp, request, acceptance and fill separately before claiming an executable result.
Use ordinary market prices for fills even if the displayed chart is transformed. Data gaps, session filters, contract rolls and adjusted equity histories can affect averages. Preserve the exact dataset and symbol settings so another reader can distinguish an input change from a change to the rule.
Handle equality, warm-up and missing observations
The exact crossing expression matters near equality. Suppose the difference between fast and slow averages on three completed bars is −0.20, 0.00 and +0.10. A rule requiring the previous difference to be less than or equal to zero and the current difference to be greater than zero triggers on the third bar. A rule requiring the previous difference to be strictly negative misses that event. Neither convention should be silently substituted after results are known.
A second sequence of −0.20, +0.10 and +0.15 contains one upward crossing, not two. The final bar remains above the slow average but does not cross it again. Distinguish a state condition such as “fast is above slow” from an event condition such as “fast has just moved above slow.” Otherwise, a strategy may add exposure on every bar when the intended rule allowed only one entry.
Warm-up also belongs in the specification. A five-observation simple average needs five observations under the ordinary full-window convention. Filling earlier missing values with zero invents prices and changes the early signals. An exponential average additionally needs a seeding rule, so two implementations can differ at the beginning even when later values converge. Record how much earlier history is loaded and when entries first become eligible.
For gaps in the input series, decide whether the lookback counts existing observations or fixed clock intervals. Five available bars across an interruption are not necessarily five uninterrupted minutes. Preserve gap flags in the research record. A credible comparison explains these boundary choices because they can affect trades even when the two plotted average lines appear almost identical at normal chart scale.
Evaluate parameters without selecting only the winner
Trying fifty fast/slow pairs produces fifty opportunities to fit noise. Publish the range of tested settings, the selection criterion and the period used to choose them. The overfitting reference explains why the best historical pair can overstate future performance even when every individual calculation is correct.
Freeze the selected rule and inspect an untouched chronological period. Include unfavorable market regimes and realistic costs. A result that depends on one narrow parameter combination or a few exceptional trades deserves a different interpretation from a broad, stable pattern across plausible settings.
Finally, keep the educational definition separate from deployment. MACD offers another transformation of related averages, but does not remove these timing and execution issues. The operational deliverable is a reproducible specification and a transparent record of outcomes, not a claim that crossing lines will reliably generate profits.
Questions and answers
Which moving-average crossover settings are best?
There is no universally best pair. A setting depends on the input, timeframe, costs and full rules. Selecting the best historical pair from many trials creates selection bias and requires fresh evaluation.
Does a crossover at the close imply an entry at that same close?
No. If the rule needs the completed close, its signal becomes known only when that observation is complete. Specify a realistic next executable opportunity or an appropriately modeled order mechanism.
Is an EMA always superior to an SMA?
No. An EMA weights recent observations more heavily, while an SMA uses an equally weighted rolling window. They have different response and initialization properties; superiority is an empirical claim, not part of the definition.
Can a 15-minute signal use the final close of its unfinished hourly bar?
No. A historical row stamped with the hour's start is not proof its final close was available then. Join on the recorded confirmation or receipt time, and use only values available before the decision.
Why does the worked 10:30 crossover disappear with an availability-time join?
The final 10:00–11:00 hourly close is not yet known at 10:30. Using it early sets the hourly SMA(2) to 98 and creates a false upward crossing; the available hourly SMA(2) is 105, and both lower-timeframe SMA values remain below it.
Does the confirmed 11:15 crossover mean a trade filled at 11:15?
No. It identifies a signal after the hourly input is available. Order creation, the next eligible execution opportunity, costs, broker response and actual fills require separate evidence.
Sources and further checks
Use the current source for your exact instrument, account and platform. Referencing a general specification does not establish support for every TradeCopier workflow.
- Fidelity: Simple Moving Average · Checked September 19, 2026
- Fidelity: Exponential Moving Average · Checked September 19, 2026
- TradingView: Repainting after refresh · Checked September 19, 2026
- TradingView: Other timeframes and lookahead · Checked September 24, 2026
- QuantConnect: Bar period and end time · Checked September 24, 2026
- pandas: merge_asof availability joins · Checked September 24, 2026
- TradingView: Strategy order and fill timing · Checked September 24, 2026
Found an error? Send a correction with this page's address and a primary source. See our editorial standards for how we handle examples, claims and revisions.